Whole of Life Insurance
Protection That Lasts a Lifetime
Most life insurance policies are designed to protect you for a specific period of time. Whole of Life Insurance is different.
Instead of ending after 20, 25 or 30 years, Whole of Life Insurance is designed to remain in place for the rest of your life, providing a lump sum to your chosen beneficiaries whenever death occurs, subject to the policy terms and premiums being maintained.
Whether your goal is to leave something behind for your family, help cover funeral expenses, or support estate planning, Whole of Life Insurance can provide valuable peace of mind that protection will still be there when it's needed.
Speak to us about finding the right lifetime protection for you and your family.
What If?
What if your family needed financial support tomorrow?
No one likes to think about what happens after they're gone, but having the right plans in place can make a difficult time a little easier for those left behind.
Without suitable protection, your loved ones may need to meet funeral expenses, deal with outstanding financial commitments, or navigate the administration of an estate without immediate access to funds.
Whole of Life Insurance provides reassurance that a lump sum could be available to help support your family's financial needs whenever the time comes.
Why Consider Whole of Life Insurance?
People choose Whole of Life Insurance for many different reasons.
You may want to:
- Leave a financial legacy for your children or grandchildren
- Help meet future funeral costs
- Support inheritance tax planning arrangements
- Provide funds that could help protect family wealth
- Ensure loved ones receive a guaranteed financial benefit whenever you die
Unlike many other forms of life insurance, the protection isn't tied to a specific deadline.
How It Works
Understanding Your Priorities
Every family is different.
We'll take time to understand what matters most to you, whether that's protecting wealth, helping your family financially, or planning for the future.
Finding the Right Type of Cover
There are several ways a Whole of Life policy can be structured. We'll explain the options clearly and help you understand the advantages and considerations of each.
Comparing Insurers
As independent advisers, we compare suitable policies from a range of insurers to help find the cover that meets your needs and budget.
Ongoing Peace of Mind
Once your policy is in place, you'll have the reassurance of knowing that your cover is designed to remain in force throughout your lifetime, provided premiums continue to be paid.

Guaranteed Premiums
Many clients prefer the certainty of knowing exactly what they'll pay throughout the life of the policy.
With a guaranteed premium plan, your payments are fixed from the outset and will not increase in the future.
This offers:
- Complete certainty
- Easier budgeting
- No surprises later in life
Although premiums can be higher initially, many clients value the long-term peace of mind this provides.
Choosing The Right Premium Option
Not all Whole of Life policies work in the same way.
One of the most important decisions is how you would like your premiums to be structured.
Unit-Linked Whole of Life
Some Whole of Life policies include an investment element.
Part of your premium is allocated to investment funds, and the performance of those investments can influence how the policy operates over time.
These arrangements can offer flexibility, but they are generally more complex and may require ongoing reviews to ensure the policy remains on track.
We'll explain the differences clearly so you can decide which approach best suits your circumstances.
Reviewable Premiums
Some policies start with lower premiums and are reviewed by the insurer at agreed intervals.
This can make cover more affordable in the early years, although future premium increases may apply depending on the insurer's review process.
Whole of Life vs Term Insurance
What's the Difference?
Both types of policy can provide valuable protection, but they are designed for different purposes.
Term Insurance
Term Insurance is usually chosen when protection is needed for a specific period of time.
For example:
- Repaying a mortgage
- Protecting a young family
- Replacing income during working years
If the policy ends before a claim is made, no benefit will normally be paid.
Whole of Life Insurance
Whole of Life Insurance is designed for situations where the need for protection is likely to remain throughout your lifetime.
It's commonly used for:
- Leaving a legacy
- Estate planning
- Inheritance tax planning
- Funeral provision
- Long-term family protection
In simple terms, Term Insurance protects against events occurring within a chosen period, while Whole of Life Insurance focuses on providing protection whenever death occurs.
David's Story
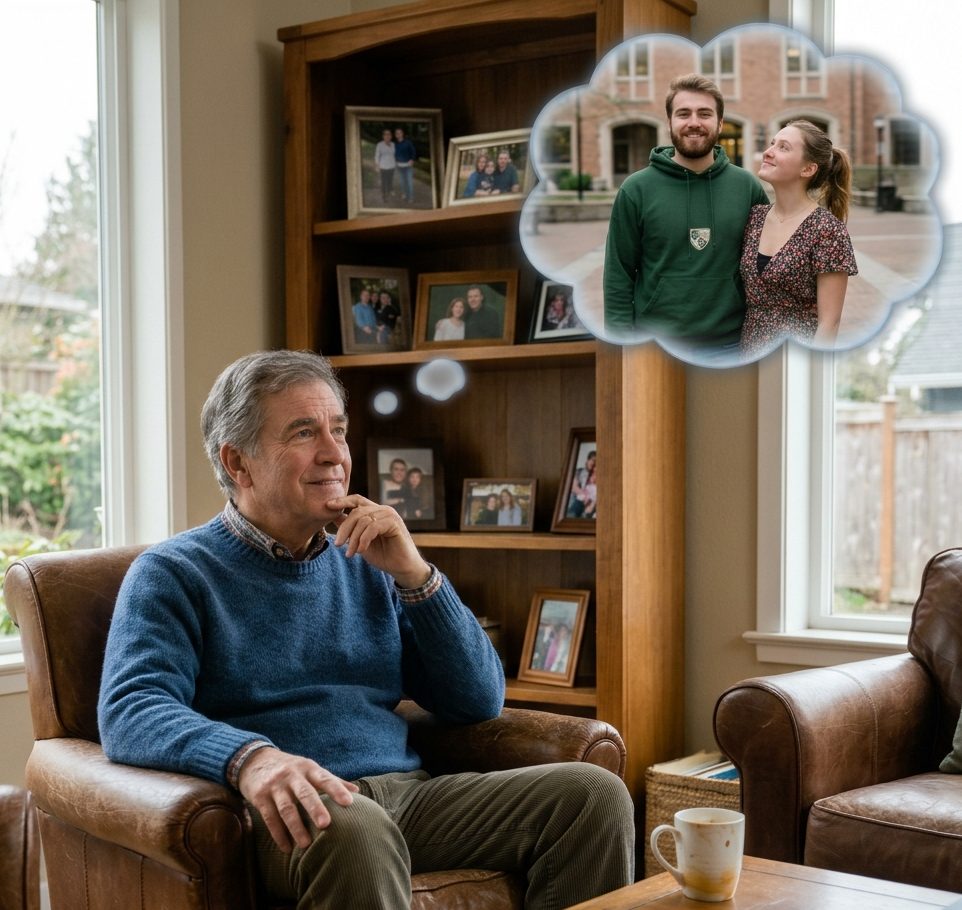
David wanted to make sure his children would receive a meaningful financial benefit regardless of when he died.
His mortgage had already been repaid and his primary concern was preserving family wealth and leaving a lasting legacy.
After reviewing his options, he chose a Whole of Life policy with guaranteed premiums, giving him confidence that the cost would remain fixed while providing lifelong protection for his family.
He also chose to use a Trust to ensure ease of settlement when the benefit was paid to his family.
Frequently Asked Questions
Is Whole of Life Insurance worth considering?
Is it more expensive than Term Insurance?
Generally, yes. Because the policy is designed to provide lifetime cover, premiums are usually higher than equivalent term policies.
Can I choose fixed premiums?
In many cases, yes. Some policies offer guaranteed premiums that remain fixed for life.
Can I Put Whole Life Insurance Into Trust?
In many cases, policies can be written into trust to help ensure proceeds are paid efficiently to your chosen beneficiaries. Professional advice should always be sought.
Can I Get Cover With Existing Medical Conditions?
Many insurers consider applicants with existing health conditions, although terms may vary depending on individual circumstances.
What is a unit-linked policy?
A unit-linked Whole of Life policy includes an investment element alongside the life insurance cover.
Rather than all of your premium being used solely to provide insurance, part of the premium is invested into funds selected by the insurer. The value and performance of those investments can influence how the policy operates over time.
This means the plan can be more flexible than a traditional guaranteed Whole of Life policy, but it can also be less predictable.
Things to Consider
- The value of investments can rise and fall.
- Investment performance may affect the long-term sustainability of the policy.
- If investment returns are lower than expected, additional premiums may be required in the future to maintain the intended level of cover.
- Regular reviews are often recommended to ensure the policy remains suitable and adequately funded.
- The overall cost during your lifetime may be difficult to predict with certainty.
Why Some People Choose Unit-Linked Policies
For some clients, a unit-linked arrangement can offer:
- Greater flexibility
- Potential investment growth
- Different premium structures to suit individual objectives
- Solutions that may support more complex estate-planning needs
Why Others Prefer Guaranteed Whole of Life Cover
Many people favour guaranteed Whole of Life policies because they provide greater certainty.
The premium is fixed from the outset, there is no investment risk, and you know exactly what the policy is designed to deliver, provided premiums continue to be paid.
For this reason, guaranteed premium Whole of Life plans are often the preferred choice where simplicity, certainty and long-term peace of mind are the primary objectives.
This wording feels less like a product manual and more like adviser-led guidance, while subtly steering visitors toward the certainty of guaranteed Whole of Life cover without overtly selling it.
Can Whole of Life Insurance help with inheritance tax planning?
It can form part of a wider estate planning strategy. We can discuss how this may work and whether it could be suitable for your circumstances.
The most suitable option depends on your objectives and financial commitments.
Can I Have More Than One Life Insurance Policy?
Yes. Many people have multiple life insurance policies for different purposes. For example, policies may cover a mortgage while another provides additional financial support for their family.
Will A Life Insurance Payout Be Subject To Inheritance Tax?
Life insurance benefits are often outside of inheritance tax planning considerations when policies are written in trust, although each situation is different. Professional legal and tax advice should be sought where appropriate.
Is It Possible to Increase My Cover Later?
Some policies include options that allow cover to be increased following major life events such as marriage, having children or moving home. Availability varies between insurers and policy types.
What Happens If I Outlive My Policy Term?
The policy is a whole life term and is intended to deliver benefits on your death.
Some unit linked policies may accumulate a surrender value after a period of time, but they are NOT investment plans and should not be considered for this purpose.
Can Self-Employed People Get Life Insurance?
Yes. Whole Life insurance is available to employed and self-employed individuals alike. In fact, self-employed people often place greater reliance on personal protection because they may not have access to the benefits that some employers provide.
Related Protection Solutions:
Family Income Benefit
Providing ongoing monthly payments rather than a single lump sum.
Critical Illness Cover
Helping provide financial support following specified serious illnesses.
Mortgage Protection
Protection designed around your mortgage commitments.
Income Protection
Helping replace part of your income if illness or injury prevents you from working.
Need Lifetime Protection?
Whether you're looking to leave a legacy for your family, help protect your estate, or simply gain peace of mind that financial support will be available when it's needed most, we're here to help.
Arrange your free protection review and discover whether Whole of Life Insurance could be right for you.
Risk Warning
Protection insurance (life, critical illness, income protection)
Cover is subject to underwriting and to terms and conditions. Please refer to the policy documents for full details. As with all insurance policies, conditions and exclusions will apply.
Whole of Life Insurance is a long-term commitment. Premiums must be maintained for cover to continue. Tax treatment depends on individual circumstances and may change in the future. Policies with investment-linked features carry additional risks and may not be suitable for everyone.